Healthcare in India: There’s more to Asia than AI
Cameron Robertson
Portfolio Manager, Platinum Asia Strategy
The AI-driven semiconductor boom has dominated Asia’s investment narrative since 2024. Yet the surge in Korean and Taiwanese chip stocks can overshadow opportunities in sectors with more predictable demand and defensive characteristics.
India’s healthcare sector is one area attracting our attention. As incomes rise, demand for healthcare can increase dramatically. Average income of around US$2,000 is often seen as a threshold for this shift, supporting the growth prospects of high-quality healthcare providers.
For investors, the opportunity lies in identifying businesses that can meet this growing demand while improving the capacity, services and profitability of their hospitals.
A growing hospital network
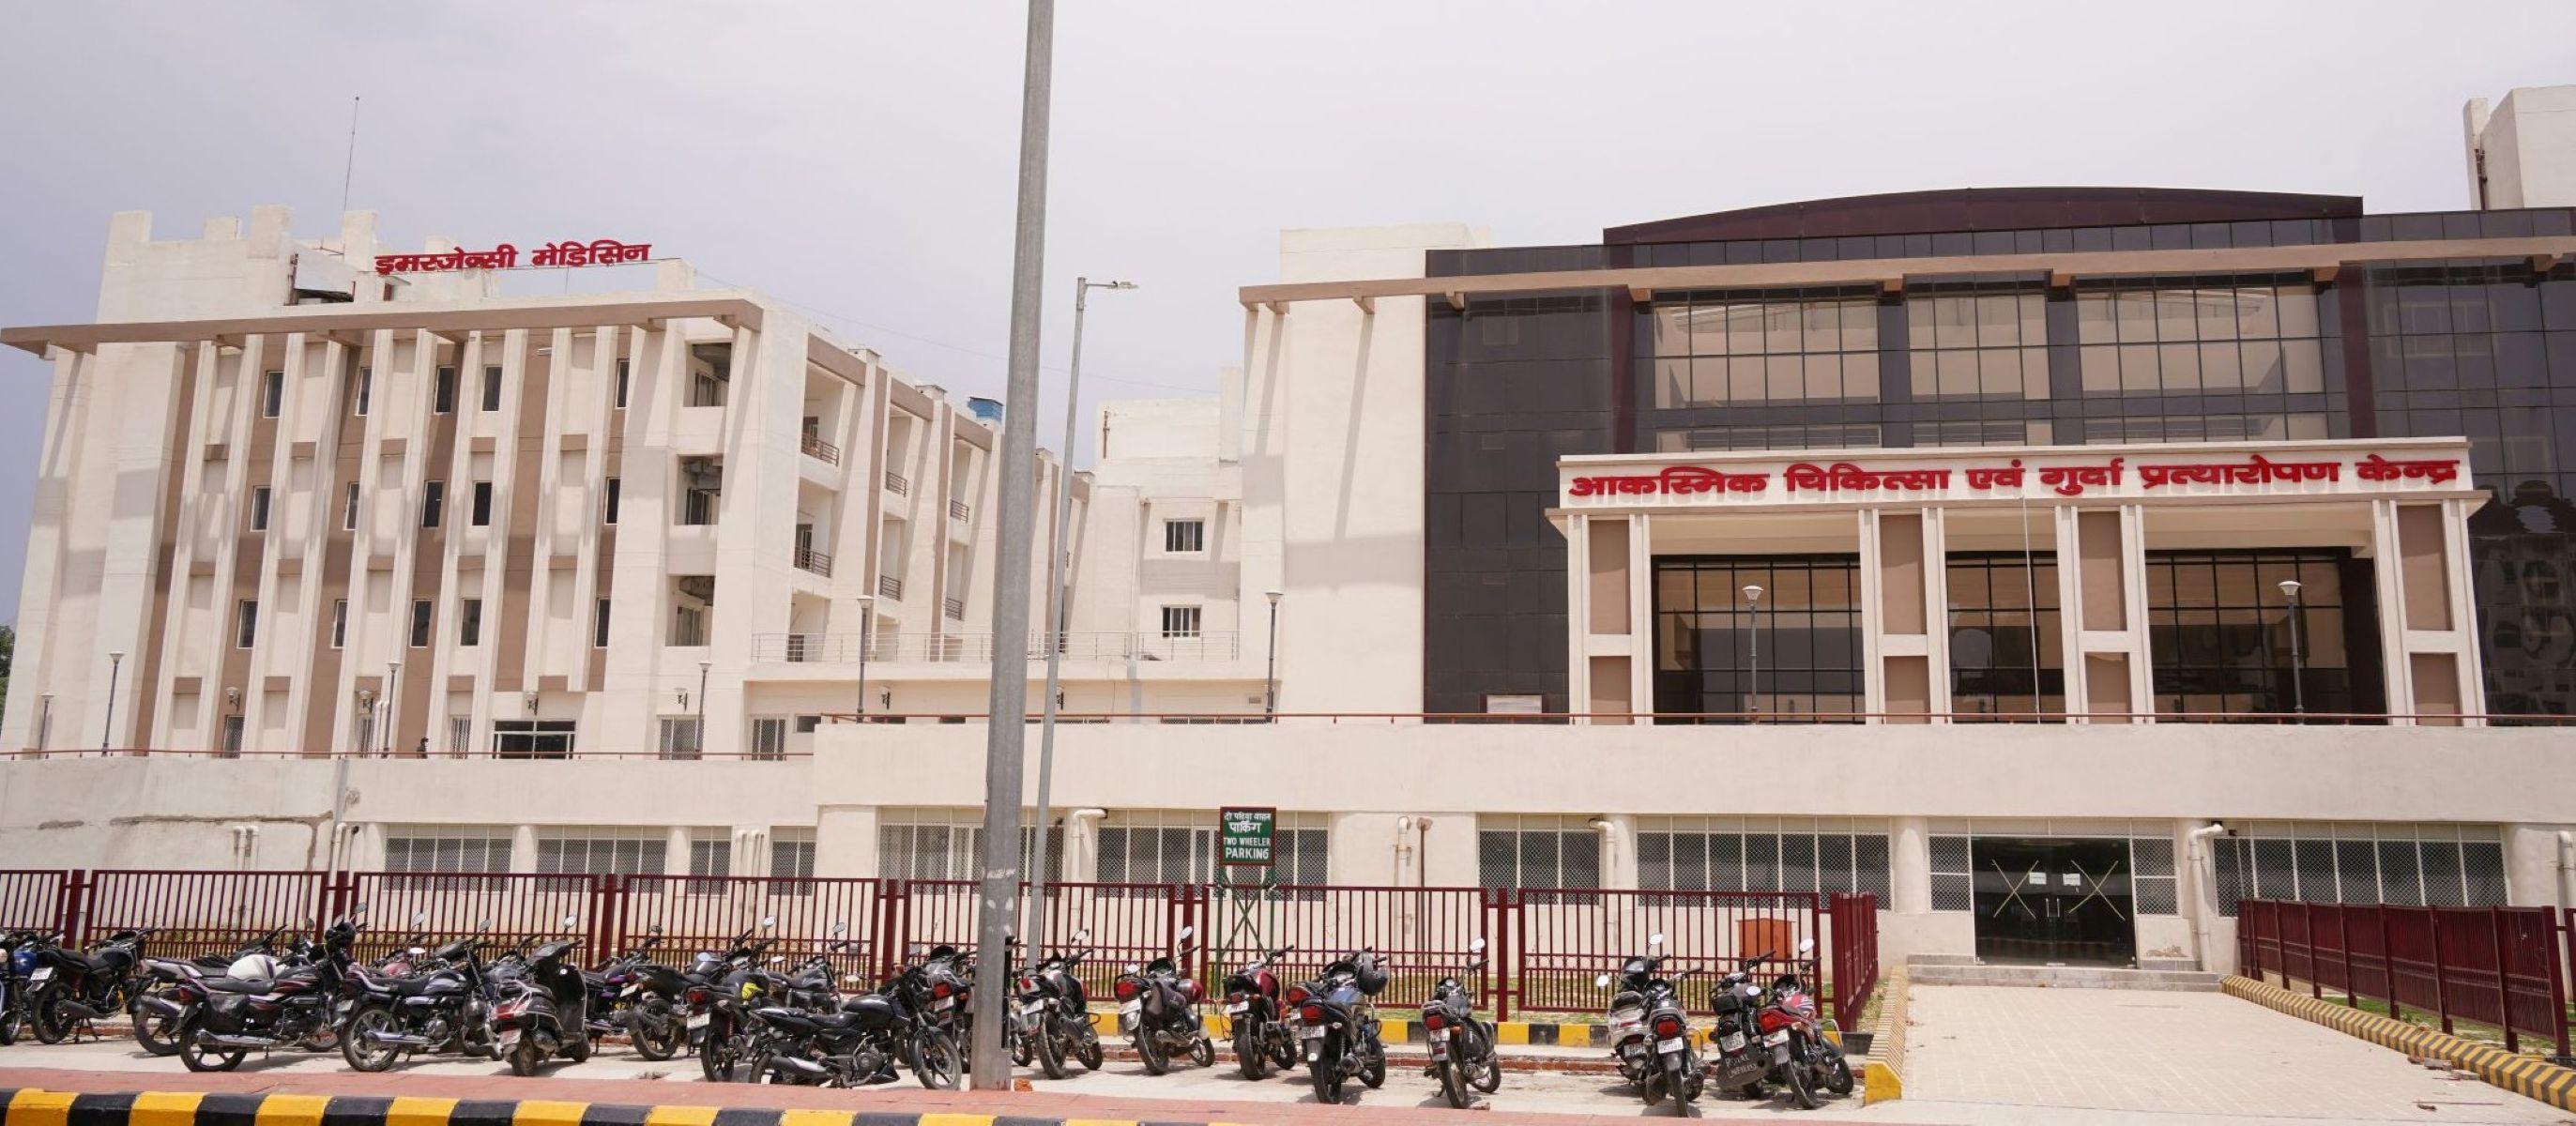
Yatharth Hospitals & Trauma Care was founded by two brothers, both orthopaedic surgeons. It now has eight hospitals and a ninth under construction across the Delhi National Capital Region.
The business grew rapidly under the founders’ management. They have since brought in professional healthcare executives to help sustain that momentum and reduce key-person risk.
Our interest in Yatharth centres on how it has expanded its network and the opportunity to improve performance across its hospitals.
Three drivers of hospital revenue
Hospital businesses have several ways to grow revenue. For Yatharth, three are particularly relevant: occupancy, case mix and payer mix.
- Occupancy is important because hospitals carry substantial fixed costs, including infrastructure, technology and staff. As more beds and operating theatres are used, much of the additional revenue can flow through to the bottom line.
- Case mix refers to the treatments a hospital provides. Adding complex specialist services, such as oncology, neurosurgery and cardiology, can generate higher revenue.
- Payer mix also matters. India’s healthcare system includes private and government payers, alongside a growing role for private health insurance. For hospital operators, attracting more private patients means higher fees and better cash flow.
Building capacity and improving services
Yatharth has expanded its bed capacity by acquiring hospitals cheaply from competitors and purchasing distressed facilities that other operators had not completed. This has allowed it to add capacity at below build cost.
It has also improved its case mix by attracting specialist doctors, running doctor training programmes and investing in the expensive technologies required for specialist surgery. Alongside these investments, Yatharth has attracted more private patients, improving its payer mix.
The results at some of its more established hospitals illustrate the potential. In a couple of its most developed facilities in the Noida area, revenue per bed has increased from 20,000 rupees per night to 50,000 rupees per night over the past four years.
We believe there is scope to extend that improvement programme across the wider network.
Valuation and the portfolio opportunity
At the time of our September 2026 quarterly report, Yatharth was trading at around 30 times earnings, a sizeable discount to Indian competitors trading at around 50 times earnings.
Although marginally more expensive than comparable hospital businesses in South East Asia, we believe Yatharth benefits from the Indian market’s more attractive structure and stronger growth prospects.
Its management, growth opportunities and defensive healthcare characteristics make it an attractive holding in the Platinum Asia Fund. It also helps balance the portfolio’s exposure to more volatile growth businesses, including semiconductor companies.
Asia’s investment opportunities extend well beyond AI. India’s healthcare sector offers a different source of growth, supported by rising incomes, increasing demand and the opportunity for well-managed operators to improve their businesses.
Discover the Platinum Asia Strategy
Explore our investment approach and the opportunities we’re finding across Asia.
Share this
This article was originally published in Platinum’s September 2026 Quarterly Report.
The above information is commentary only (i.e. our general thoughts). It is not intended to be, nor should it be construed as, investment advice. To the extent permitted by law, no liability is accepted for any loss or damage as a result of any reliance on this information. Before making any investment decision you need to consider (with your financial adviser) your particular investment needs, objectives and circumstances.
Related Journals
View all related reads
The Next Asian Winners May Not Be AI with Cameron Robertson | Equity Mates
From AI infrastructure to healthcare and consumer businesses, explore the opportunities shaping Asia’s diverse markets. Scroll down to watch the interview.
September 2026 Investor Update | Platinum International Fund
David Steinthal, Portfolio Manager of the Platinum International Fund, discusses the current investment environment, the ongoing impact of artificial intelligence on markets and company fundamentals, and why Platinum continues to see compelling long-term opportunities across much of the portfolio.
Platinum Asia Fund | Investor Update
Watch Cameron Robertson, Portfolio Manager of the Platinum Asia Strategy, discuss the forces shaping Asian markets, emerging growth opportunities and long-term themes for the Platinum Asia Fund. Released 1 September 2026.